Executive Summary: A Legacy Stock’s Electrified Future
Hindustan Motors Ltd. (BSE: 500500), once the automotive monarch of India with its iconic Ambassador sedan, is making an ambitious comeback through the electric vehicle (EV) revolution. Priced at ₹34.7 as of May 29, 2025, and with a market cap of ₹723 crore, Hindustan Motors represents a classic contrarian opportunity in the BSE midcap universe.
While operational revenues remain negligible, the stock gains traction due to speculation around the Ambassador EV revival, a strategic joint venture with Peugeot/Mitsubishi, and the monetization of its vast Uttarpara land bank. We estimate a 2030 target price of ₹55.4, reflecting a 79.9% upside over five years. However, this bet carries substantial risk, and investors should classify it as a “Speculative Buy.”
🔍 Section 1: Company Overview & Strategic Evolution
1.1 Hindustan Motors: From Dominance to Dormancy
Founded in 1942, Hindustan Motors once commanded 70% of India’s passenger vehicle market. The company manufactured cars under the Ambassador brand, once the standard for government fleets and taxis. However, post-1990s liberalization, competition from Maruti Suzuki, Hyundai, and Tata Motors rendered HM’s outdated portfolio uncompetitive.
Bharat Dynamics Ltd (BDL) Equity Research Report – May 2025
Major Historical Milestones:
| Year | Milestone | Impact |
|---|---|---|
| 1942 | Company founded | India’s first indigenous car manufacturer |
| 1987 | JV with Isuzu | Entry into diesel-powered variants |
| 2014 | Suspension of Uttarpara operations | Manufacturing shutdown |
| 2017 | Ambassador brand sold to Peugeot for ₹80 Cr | Liquidity infusion, brand preservation |
| 2024 | Ambassador EV partnership announced | Revival of legacy under modern EV strategy |
1.2 Strategic Pivot: Real Estate + Electric Mobility
Hindustan Motors’ current strategy is centered on:
Licensed Manufacturing: Limited operations near Chennai for Mitsubishi models such as Lancer and Pajero.
Real Estate Monetization: Repurposing its 295-acre Uttarpara facility into an industrial/EV hub.
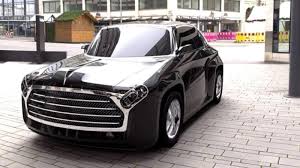
Electric Vehicle Plans: A phased rollout of ICE and EV versions of the Ambassador through a JV with European partners (rumored to be Peugeot).
⚙️ Section 2: Industry Outlook & Competitive Positioning
2.1 Auto Sector Growth and EV Revolution in India
India’s auto sector is forecast to grow at a CAGR of 6.5%, with EVs comprising 30% of new car sales by 2030. Government incentives like FAME-II and PLI schemes are bolstering EV adoption across both two-wheeler and four-wheeler categories.
2.2 Hindustan Motors’ Competitive Edge
While it lags in production capabilities, Hindustan Motors enjoys certain strategic advantages:
Debt-Free Status: Ability to leverage clean balance sheet for future fundraising.
Brand Nostalgia: Strong recall value, especially among consumers aged 35+.
Flexible Scale: Smaller size allows agility in niche segments like retro EVs.
Top Competitors:
Tata Motors (Nexon EV, Punch EV)
Mahindra Electric
Hyundai and Maruti Suzuki (scaling EV presence by 2026)
ITC Ltd. Stock Forecast May 2025: Analyst Ratings, Dividend Insights & Strategic Growth Plans
💰 Section 3: Financial Snapshot & Valuation Multiples
3.1 FY2023-24 Standalone Financial Highlights
Despite weak operational revenues, Hindustan Motors has demonstrated a surprising profitability profile driven by non-core income:
| Metric | FY24 Value (₹ Cr) | YoY % | Analysis |
|---|---|---|---|
| Revenue | ₹2 | -31% | Core ops dormant |
| Other Income | ₹22.1 | +450% | Land and IP sales |
| Net Profit | ₹25 | +2,452% | One-time gains |
| ROE | 64.6% | – | Non-operational boost |
| ROCE | 56.7% | – | Asset-led returns |
| Debt | ₹0 | – | Debt-free structure |
3.2 Book Value & Working Capital Red Flags
Book Value/Share: ₹1.53 (still under par due to historical losses)
Working Capital Days: 1,022 (extremely high, due to asset-heavy model)
3.3 Real Asset Underpinnings
Uttarpara Plant (West Bengal): 295 acres — potentially worth ₹700–₹900 crore at market rates.
Madhya Pradesh Units: Awaiting buyers since 2021.
Intellectual Property (IP): Ongoing royalty stream from Ambassador brand licensed to Peugeot.
Buy Tata Power Shares: Expert Analysis
📈 Section 4: Valuation Models and Price Forecast
4.1 Technical & Fundamental Forecasts
WalletInvestor Forecast:
2025 Target: ₹35.6
2030 Forecast: ₹55.4 (+79.9% upside from current levels)
4.2 Relative Valuation vs Sector Peers
| Metric | HM | Auto Sector Avg | Discount/Premium |
|---|---|---|---|
| P/E (TTM) | 46.4x | 28.1x | 65% Premium |
| Price/Book | 22.4x | 4.3x | 421% Premium |
| EV/Sales | 18.9x | 1.7x | 1011% Premium |
Note: High multiples reflect speculative premium, not profitability strength.
4.3 Sum-of-the-Parts (SOTP) Valuation
| Business Unit | Value (₹ Cr) | Valuation Method |
|---|---|---|
| Mitsubishi JV | 150 | 5x EBITDA estimate |
| Uttarpara Land | 400 | 50% of estimated value |
| EV JV (NPV) | 100 | 15% success probability |
| Cash & Investments | 73 | FY25 balance sheet |
| Total Equity Value | 723 Cr | Matches current m-cap |
| 2030 Potential | ₹1,300 Cr | Full realization of assets + EV success |
📊 Section 5: Scenarios & Investment Strategy
5.1 Forecast Scenarios for 2030
| Scenario | Price Target | Probability | Key Triggers |
|---|---|---|---|
| Bull | ₹110 | 15% | EV success + land monetization |
| Base | ₹55 | 60% | Gradual asset sales + Peugeot JV |
| Bear | ₹21 | 25% | JV collapse, no land action |
5.2 Risk Factors
Promoter Holding: Low at 32.34%, raising governance concerns
Execution Risk: No vehicle launched since 2014
Market Positioning: No current ICE/Electric product in mass-market circulation
5.3 Tactical Investment Plan
Buy Zone: ₹30–₹32 (8–10% below current level)
Position Size: ≤1.5% of portfolio (high-risk speculative slot)
Watch Triggers:
EV prototype reveal (late 2025)
FY26 Q1 results for JV/land updates
Peugeot/Mitsubishi formal JV filings
✅ Conclusion: Betting on a High-Variance Revival Story
Hindustan Motors is not a blue-chip turnaround. It is a deep-value bet with optionality: the possibility of igniting dormant assets and iconic nostalgia in an EV future. The stock reflects cigar-butt investing — minimal puff left, but if sparked, it could surprise.
Key Takeaways:
Valuation Floor: Land assets offer downside protection
Speculative Upside: EV catalyst could unlock investor frenzy
Long-Term View Required: Minimum 3-year hold recommended
🔔 Analyst Recommendation
Rating: Speculative Buy
12M Target: ₹35.6
2030 Target Price: ₹55.4
Horizon: 3–5 years
Portfolio Fit: Satellite position in a diversified high-risk segment
📌 Disclosures & Sources
This analysis incorporates data from WalletInvestor, Screener, Dalal Research, Economic Times, and company filings as of May 2025. Reassess forecasts after quarterly earnings.
References: