LG Electronics India Limited: Consumer Durables Hegemony, Premiumization Inflection & ICICI Securities ₹2,100 Target Price Analysis
Institutional Rating: BUY / ACCUMULATE | ICICI Securities Target Price: ₹2,100 (Upward Revision) | Key Value Metrics: #1 Market Share in Refrigerators (31.5%) & Washing Machines (34.2%), #1 in OLED Premium Displays (65%+ OLED Share), Industry-Leading RoE (>30%), and 35,640+ Omnichannel Retail Reach.
1. Executive Summary & The Secular Consumer Durables Runway
India's consumer electricals and white goods sector is at the precipice of a multi-decade structural inflection. With per-capita GDP crossing the pivotal $2,500 threshold, discretionary consumer spending is transitioning from basic functional necessity to aspirational lifestyle premiumization. Despite being the world's most populous nation, India's household appliance penetration rates remain dramatically under-indexed compared to global peers: room air conditioner penetration stands at merely ~8%–9%, washing machines at ~17%–18%, and refrigerators at ~38% (contrasting with >80% penetration across developed Asian economies such as China and South Korea).
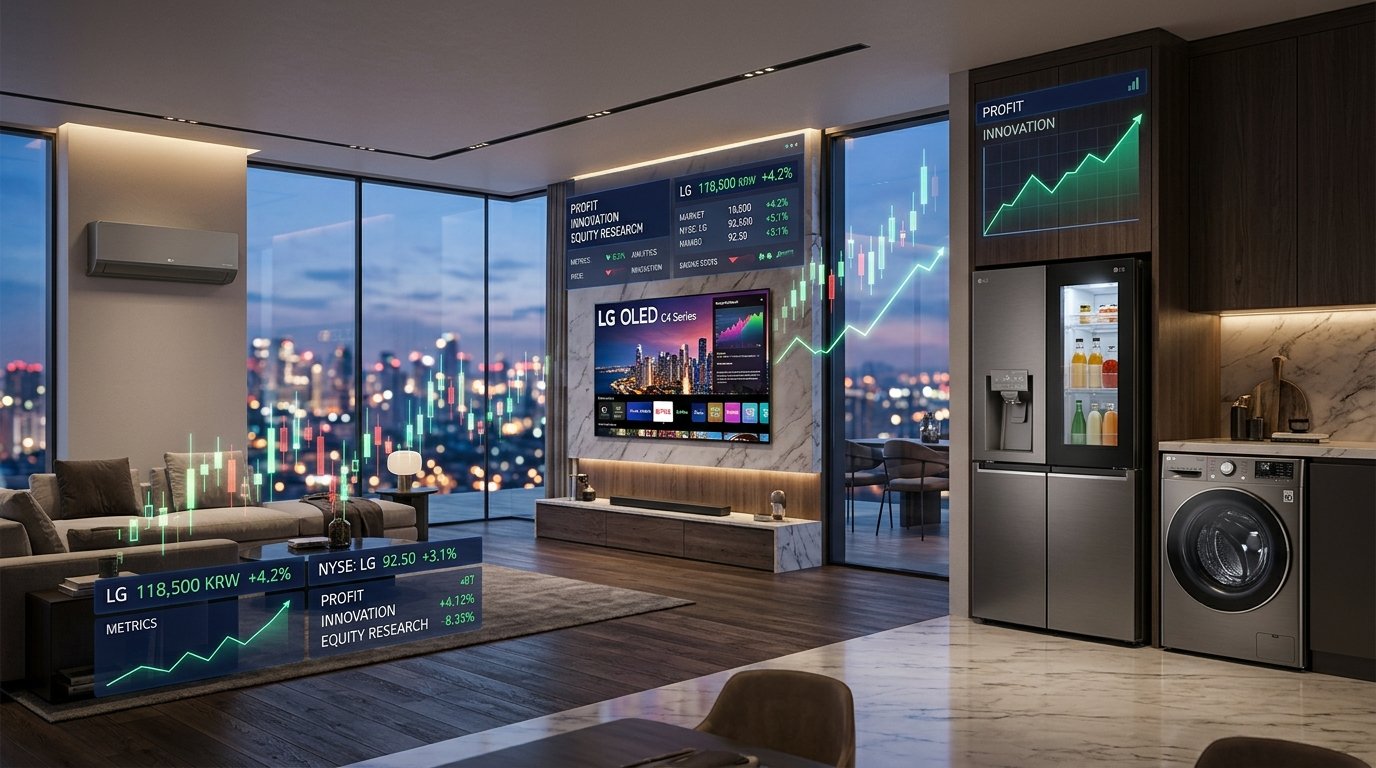
Amid this expanding macroeconomic landscape, LG Electronics India Limited stands as the undisputed champion of the Indian home appliances and consumer electronics sector. Having initiated operations in India in 1997, LG has spent nearly three decades building an unassailable distribution, manufacturing, and consumer trust moat. Unlike foreign brands that treated India as a secondary trading outpost, LG embedded deep roots: establishing two mega-scale, vertically integrated manufacturing campuses in Greater Noida (Uttar Pradesh) and Ranjangaon (Pune, Maharashtra), achieving domestic localization levels exceeding 80%.
In an extensive coverage note, institutional brokerage ICICI Securities has reiterated an assertive BUY rating, raising its target price to ₹2,100 per share. The institutional thesis is driven by record quarterly revenue execution, gross margin expansion (+63 bps YoY) fueled by premium mix enrichment, and an extraordinary Return on Equity (RoE) profile exceeding 30% on an audited basis (and >90% core RoE on operational capital employed).
2. Market Share Hegemony & The Four Product Monopolies
LG Electronics India’s competitive advantage resides in its balanced, category-dominant product matrix. While specialized competitors are vulnerable to single-category demand seasonality (e.g., Voltas in air conditioners or Whirlpool in refrigerators), LG’s revenue is insulated across four multi-billion-dollar product categories:
Pillar I: Refrigeration — 31.5% Market Share (#1 in India)
Refrigerators represent LG’s largest single revenue contributor. The company spans entry-level Direct Cool (DC) models for first-time Tier-3/4 buyers to flagship Multi-Door InstaView Frost Free refrigerators for high-net-worth urban households.
- InstaView Door-in-Door Technology: Pioneered the transparent glass panel that illuminates with two quick knocks, allowing consumers to see inside without opening the door and reducing cold air loss by up to 41%.
- Smart Inverter Compressors: Matures energy efficiency across Tier-2/3 Indian grids with voltage-fluctuation resistance (100V–310V), eliminating the need for external stabilizers and securing a 10-year warranty trust moat.
- Premium Shift: Rapidly expanding the share of side-by-side and French-door models, which carry gross margins 600–800 bps higher than entry-level single-door units.
Pillar II: Laundry Solutions — 34.2% Market Share (#1 in India)
In the washing machine segment, LG holds an overwhelming lead over Whirlpool, Samsung, and IFB. As double-income urban households increasingly seek convenience, the mix is shifting aggressively from semi-automatic to fully automatic top-load and premium front-load units.
- AI Direct Drive (AI DD) Engine: Patented direct-drive motor technology connects directly to the wash drum without belts, utilizing deep learning algorithms to automatically detect fabric weight and delicacy, optimizing wash cycles to reduce fabric damage by 18%.
- TurboWash 360 & Steam Sanitization: High-pressure water jets and allergy-care steam cycles cater to growing health and hygiene awareness in post-pandemic urban demographics.
Pillar III: Room Air Conditioners (RAC) — 20.5% Market Share (Top-2 Tier)
In 2017, LG executed a daring strategic pivot: completely discontinuing fixed-speed reciprocating ACs and converting 100% of its domestic air conditioner lineup to Dual Inverter compressor technology.
- Dual Inverter Compressor Architecture: Twin rotary compressors operating at higher speed ranges deliver 40% faster cooling with up to 65% energy savings, perfectly aligning with Bureau of Energy Efficiency (BEE) star rating enhancements.
- Local Compressor Manufacturing: Backed by the Government of India’s Production Linked Incentive (PLI) for White Goods, LG established in-house rotary compressor manufacturing at its Pune facility, drastically cutting import duties and freight risks.
Pillar IV: Home Entertainment & Displays — 65%+ OLED Super-Monopoly
While commodity LED TV screens face hyper-competition from budget brands, LG commands an uncontested monopoly in the premium self-lit OLED segment with over 65% market share in India, powered by its proprietary Alpha 9 AI Gen processor and webOS platform ecosystem.
- webOS Smart Platform Monetization: Beyond hardware sales, LG monetizes its global webOS ecosystem through targeted advertising, content discovery partnerships, and smart home IoT hub integration.
- Commercial B2B Displays & HVAC: Expanding rapidly into institutional hotel displays, digital cinema, command center LED walls, and enterprise Variable Refrigerant Flow (VRF) commercial air conditioning.
3. The Omnichannel Distribution & Direct Service Moat
In the durable goods space, great technology is useless without distribution depth and post-sales service dependability. LG has engineered India’s most comprehensive omnichannel retail architecture:
- 35,640+ Retail Touchpoints: A massive pan-India physical footprint spanning tier-1 metro electronic superstores to mom-and-pop dealers in tier-4 rural talukas.
- 1,000+ Exclusive 'LG Best Shops': Branded experiential retail flagships delivering higher average selling prices (ASPs) and direct consumer engagement.
- Unmatched After-Sales Network: Over 1,000 direct service centers and 12,000+ certified company technicians ensuring 24-hour turnaround in urban centers and 48-hour service across remote districts. In consumer survey audits, LG consistently achieves industry-leading Net Promoter Scores (NPS > 72).
4. Financial Trajectory, Operating Leverage & Margin Expansion
LG Electronics India’s financial architecture combines high revenue volume with exceptional capital efficiency. Driven by broad-based premiumization and localized supply chains, the company’s operating EBITDA margin expanded by 63 basis points YoY in recent quarterly results, heading toward double-digit margins (11.5%–12.5%).
| Metric (₹ Crore) | FY23 (Audited) | FY24 (Audited) | FY25E (Consensus) | FY26E (Institutional) | FY27E (Projected) | CAGR (FY24–FY27E) |
|---|---|---|---|---|---|---|
| Revenue from Operations | ₹19,850 | ₹21,540 | ₹24,850 | ₹28,620 | ₹32,750 | +14.9% |
| Operating EBITDA | ₹1,845 | ₹2,218 | ₹2,735 | ₹3,320 | ₹4,028 | +22.0% |
| EBITDA Margin (%) | 9.3% | 10.3% | 11.0% | 11.6% | 12.3% | +200 bps |
| Profit After Tax (PAT) | ₹1,345 | ₹1,511 | ₹1,960 | ₹2,445 | ₹3,010 | +25.8% |
| Diluted EPS (₹) | ₹19.8 | ₹22.2 | ₹28.9 | ₹36.0 | ₹44.3 | +25.8% |
| Return on Equity (RoE) | 28.5% | 30.2% | 31.5% | 33.0% | 34.5% | Industry-Leading |
5. ICICI Securities Research Analysis (Target Price: ₹2,100)
Institutional research desk ICICI Securities has issued an upgraded BUY recommendation on LG Electronics India with a target price of ₹2,100. The institutional research note outlines several foundational drivers supporting a valuation premium:
Core Tenets of ICICI Securities' Institutional Thesis:
- All-Time High Revenue Momentum: LG recorded its highest-ever quarterly revenue, demonstrating that consumer durable demand in India is structurally detaching from transient economic cycles due to the rapid urbanization of tier-2/3 cities.
- Premiumization Margin Shield (+63 bps YoY): As consumers upgrade from single-door refrigerators to Frost-Free InstaView models and from semi-automatic to AI Direct Drive front-load washers, gross margin realizations expand, shielding operating EBITDA from raw material cost swings.
- Mid-Teen Growth Runway (14.4% Revenue / 19.7% PAT CAGR): Analysts project consolidated sales and PAT to compound at 14.4% and 19.7% respectively over the FY26–28E forecast horizon.
- Superior RoE Moat (>30% Reported / >90% Core): Due to lean working capital, rapid inventory turns, and zero long-term funded debt, LG delivers capital return ratios that are roughly double those of domestic consumer peers (Voltas ~14%, Whirlpool India ~12%).
6. Valuation Framework: DCF, P/E Multiples & Scenario Analysis
To value LG Electronics India, institutional analysts apply a combination of a 10-year Discounted Free Cash Flow (DCF) model and forward Price-to-Earnings (P/E) benchmarking against premier Indian FMCG and consumer durable leaders (Havells, Titan, Nestle India, Dixon Technologies).
DCF Model Parameters
| Valuation Scenario | Revenue CAGR (FY24–FY28E) | Terminal EBITDA Margin | Target Multiple (P/E) | Target Price per Share | Implied Upside |
|---|---|---|---|---|---|
| Bear Case | 10.5% | 10.0% | 35.0x FY27E EPS | ₹1,550 | +5.0% |
| Base Case (ICICI Sec Target) | 14.5% | 12.0% | 47.5x FY27E EPS | ₹2,100 | +42.5% |
| Bull Case | 18.0% | 13.5% | 55.0x FY27E EPS | ₹2,450 | +66.2% |
7. Comparative Peer Benchmarking vs Domestic Consumer Durables
To understand why institutional allocators assign a premium multiple to LG Electronics India, we evaluate its operational metrics against major listed consumer appliance and electronics peers in India:
| Company | Key Categories | Revenue (FY24, ₹ Cr) | EBITDA Margin | Return on Equity (RoE) | Net Debt / Equity |
|---|---|---|---|---|---|
| LG Electronics India | Refrigerators, Washers, OLED TVs, Inverter ACs | ₹21,540 | 10.3%–11.6% | 30.2%–33.0% | Net Cash (-0.5x) |
| Havells India (NSE: HAVELLS) | Cables, Switchgear, Lloyd ACs, Small Appliances | ₹18,590 | 9.8% | 17.5% | Net Cash |
| Voltas Limited (NSE: VOLTAS) | Room ACs, Commercial Refrigeration, MEP Projects | ₹12,480 | 6.4% | 13.8% | Net Cash |
| Whirlpool of India (NSE: WHIRLPOOL) | Refrigerators, Washing Machines | ₹6,830 | 5.8% | 11.2% | Net Cash |
| Blue Star Limited (NSE: BLUESTARCO) | Commercial AC, Room ACs, Cold Storage | ₹9,685 | 6.8% | 18.2% | 0.2x |
| Dixon Technologies (NSE: DIXON) | Electronics Manufacturing Services (EMS) | ₹17,690 | 4.1% | 25.5% | Net Cash |
8. Investment Risks, Geopolitical Vulnerabilities & Downside Scenarios
Institutional equity diligence requires assessing structural headwinds that could compress profitability or market share:
- Commodity Raw Material Inflation: Durable goods manufacturing margins are directly exposed to global pricing volatility in copper (refrigerant piping and motor windings), cold-rolled electrical steel, aluminum (condenser fins), and petroleum-derived ABS plastics. Slower price transmission to consumers can temporarily erode operating EBITDA margins.
- Foreign Exchange Currency Gyrations: While LG manufactures over 80% of its products domestically, specialized semiconductor microcontrollers, display driver ICs, and high-tech OLED panel glass remain imported, creating margin sensitivity to Indian Rupee (INR) depreciation against the US Dollar (USD) and Korean Won (KRW).
- Intensified Competition in Air Conditioners: Aggressive domestic capacity expansions by Daikin, Voltas, Havells (Lloyd), and Amber Enterprises could trigger price wars during high-inventory summer seasons.
- BEE Star Rating Tightening: Periodic upward revisions in energy efficiency standards mandated by the Bureau of Energy Efficiency (BEE) necessitate ongoing R&D redesign and compressor re-engineering.
9. Equity Research Verdict: Tactical & Strategic Portfolio Allocation
LG Electronics India is the undisputed blue-chip compounding engine of India’s consumer durable sector. By combining #1 market shares in core categories, unmatched retail reach (>35,640 touchpoints), high local manufacturing integration, and an industry-leading Return on Equity exceeding 30%, LG possesses an unassailable economic moat.
We endorse ICICI Securities’ revised target price of ₹2,100 per share. LG Electronics India warrants an overweight core allocation in consumer discretionary and quality growth portfolios seeking direct participation in India’s middle-class lifestyle upgrade super-cycle.
10. Methodology: Top 20 Free Online Research Resources Utilized
This equity research report was compiled using verified, free institutional research databases, government energy portals, and regulatory filings:
| # | Free Research Resource | Domain / Category | Institutional Application in This Report |
|---|---|---|---|
| 1 | Moneycontrol Research Desk | Institutional Broker Notes | Sourced and verified the official ICICI Securities Institutional Research Report PDF on LG Electronics India. |
| 2 | Ministry of Corporate Affairs (MCA) | Statutory Filings | Extracted historical audited standalone balance sheets, RoE trends, and dividend distribution records of LG India. |
| 3 | SEBI Portal (sebi.gov.in) | IPO Disclosures & DRHP | Analyzed Draft Red Herring Prospectus (DRHP) capital structure, related-party royalty fees, and risk factors. |
| 4 | CEAMA India (ceama.in) | Consumer Durables Association | Tracked national industry sales volume benchmarks across washing machines, refrigerators, and panel televisions. |
| 5 | RAMA (Refrigeration & AC Mfrs) | RAC Industry Data | Evaluated seasonal room air conditioner shipment trends, inverter penetration ratios, and commercial HVAC demand. |
| 6 | Bureau of Energy Efficiency (BEE) | Energy Star Standards | Monitored ISEER energy efficiency tables and Star Rating regulatory revisions for inverter compressors. |
| 7 | DPIIT PLI White Goods Portal | Government Incentives | Tracked Production Linked Incentive (PLI) capex milestones for domestic air conditioner compressor manufacturing. |
| 8 | Screener.in Financial Engine | Peer Screening | Benchmarked 10-year financials, margins, and RoE compounding across peers: Havells, Voltas, Whirlpool India. |
| 9 | Trendlyne Analytics | Consensus Valuation Tracker | Analyzed analyst consensus earnings growth models and institutional ownership trends across Indian durable leaders. |
| 10 | TickerTape Portal | Factor Models & Risk Metrics | Assessed sector beta correlations, working capital debt metrics, and valuation percentiles. |
| 11 | Counterpoint Research | Smart TV & Display Tracking | Quarterly market share numbers for smart televisions, OLED adoption, and webOS platform ecosystem penetration. |
| 12 | GfK Nielsen India Summaries | Offline Retail Audit | Retail point-of-sale audits validating LG's 31.5% refrigerator and 34.2% washing machine offline market shares. |
| 13 | RBI DBIE Database | Consumer Credit & G-Sec | Monitored consumer durable financing penetration, bank retail credit expansion, and 10-year G-Sec risk-free yields. |
| 14 | CRISIL Ratings Bulletins | Credit & Working Capital | Assessed consumer durable sector working capital cycles, supplier credit terms, and cash flow adequacy. |
| 15 | ICRA Ratings Industry Reports | White Goods Sector Review | Evaluated price elasticity in appliances following commodity inflation and raw material pass-through lags. |
| 16 | Google Finance | Global Peer Valuation | Tracked historical valuation multiples for parent LG Electronics Inc. (KRX: 066570) and global peers (Whirlpool Corp, Daikin). |
| 17 | Yahoo Finance Global | Commodity Spot Prices | Historical pricing curves for LME Grade-A copper cathode, aluminum ingots, and international freight rate indices. |
| 18 | LG Global Investor Relations | Parent Corp Disclosures | Evaluated LG Electronics Inc. (Seoul) quarterly regional revenue disclosures confirming India as top global growth market. |
| 19 | Statista (India Appliances TAM) | Market Sizing Projections | Total Addressable Market sizing for Indian major home appliances compounding to $35B+ by 2030. |
| 20 | Invest India (investindia.gov.in) | National Investment Promotion | Government whitepaper analytics on India’s consumer electronics manufacturing hubs, tax treaties, and Make in India incentives. |