Executive Summary
Portfolio diversification is the only "free lunch" in financial economics. By distributing capital across uncorrelated asset classes, sectors, and geographies, investors mathematically compress portfolio drawdown risk without sacrificing expected compound annual growth rate (CAGR). Below is an actionable framework tailored specifically to Indian retail and HNI investors navigating domestic market cycles.
1. Why Diversify? The Mathematics of Asymmetric Risk
Concentrated portfolios create the illusion of superior conviction until a systemic shock occurs. In the 2008 Global Financial Crisis, single-sector real estate and banking investors experienced permanent capital impairment exceeding 70%. Conversely, during the March 2020 pandemic crash, while travel and hospitality equities plummeted, healthcare and pharmaceutical leaders (such as Dr. Reddy’s Laboratories and Sun Pharma) delivered immediate counter-cyclical alpha.
True diversification protects your financial longevity by ensuring no single business failure, regulatory intervention, or cyclical downturn can compromise your family’s net worth.
2. The Four Pillars of Strategic Diversification
A. Asset Class Diversification
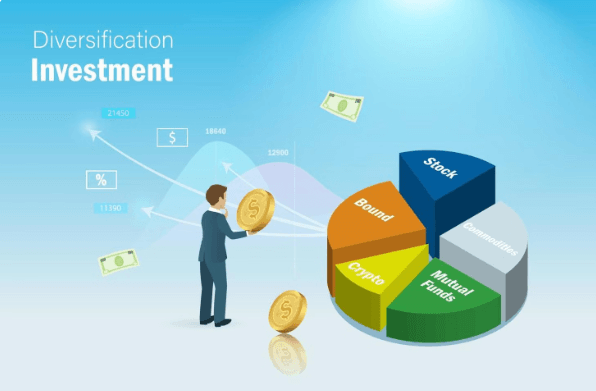
Distribute wealth across four fundamental economic buckets:
- Equities (Growth Engine): Broad-market index funds (Nifty 50, Nifty Next 50) and active flexi-cap funds designed to beat inflation by 4–7%.
- Fixed Income / Debt (Capital Preservation): Public Provident Fund (PPF), Target Maturity Debt ETFs, and high-grade corporate bond funds providing predictable liquidity.
- Precious Metals (Currency Hedge): Sovereign Gold Bonds (SGB) or Gold ETFs acting as a shock absorber against rupee depreciation and geopolitical conflict.
- Real Estate / REITs (Yield Generation): Liquid REITs (e.g., Brookfield India, Embassy Office Parks) offering commercial rental yields without property management friction.
B. Sectoral Diversification
Avoid overweighting cyclical industries. A disciplined Indian equity portfolio allocates across non-correlated sectors:
- Banking & Financials (BFSI): HDFC Bank, ICICI Bank (Credit cycle exposure)
- Information Technology (IT): TCS, Infosys (Global enterprise tech spending)
- Fast-Moving Consumer Goods (FMCG): Hindustan Unilever, Nestlé India (Defensive cash flows)
- Healthcare & Pharma: Sun Pharma, Cipla (Inelastic demand)
C. Market Capitalization Spectrum
Pair the fortress stability of Large-Caps (top 100 listed firms) with the high-operating-leverage growth potential of Mid-Caps and select Small-Caps.
D. Geographic Diversification
Domestic Indian investors often suffer from severe "Home Bias". Allocating 10–15% into US and global equity feeder funds (such as Motilal Oswal NASDAQ 100 or S&P 500 Index Funds) captures global technology monopolies while insulating capital from emerging market currency slippage.
Institutional Model Portfolio: Balanced Indian Investor
Recommended asset allocation for a 7–10 year compounding horizon:
3. Three Fatal Mistakes in Portfolio Construction
- Over-Diversification (Diworsification): Owning 12+ mutual funds. When you hold multiple large-cap funds, they usually own the identical 35 stocks (Reliance, HDFC Bank, ICICI Bank, Infosys). You pay duplicate expense ratios while achieving sub-par index returns.
- Ignoring Rebalancing: When a stock or sector surges past 20% of your total net worth, unmanaged risk doubles. Rebalance annually back to your target percentages by trimming winning assets and accumulating undervalued asset classes.
- Cash Drag: Leaving 40% of net worth in zero-yielding bank savings accounts eroding against 6% retail CPI inflation.
Frequently Asked Questions (FAQ)
How many individual stocks are needed for optimal diversification?
Academic research in empirical portfolio theory proves that holding between 15 to 25 carefully selected non-correlated stocks eliminates over 90% of unsystematic company-specific risk. Adding more than 30 stocks adds cognitive fatigue without meaningful risk reduction.
Is gold still an essential asset for young investors?
Yes. Even a 5% to 10% allocation in Sovereign Gold Bonds (SGB) provides significant insurance against black swan economic crashes, currency devaluation, and geopolitical recessions.
💡 Simulate Your Portfolio Allocations
Use our interactive financial calculator to backtest compounding outcomes under different asset allocations:
Open Financial Calculator →